With 61 million hectoliters filling Italian cellars and white IGT stocks surging 10.5%, Unione Italiana Vini demands a legislative pivot to balance supply with shifting global demand.
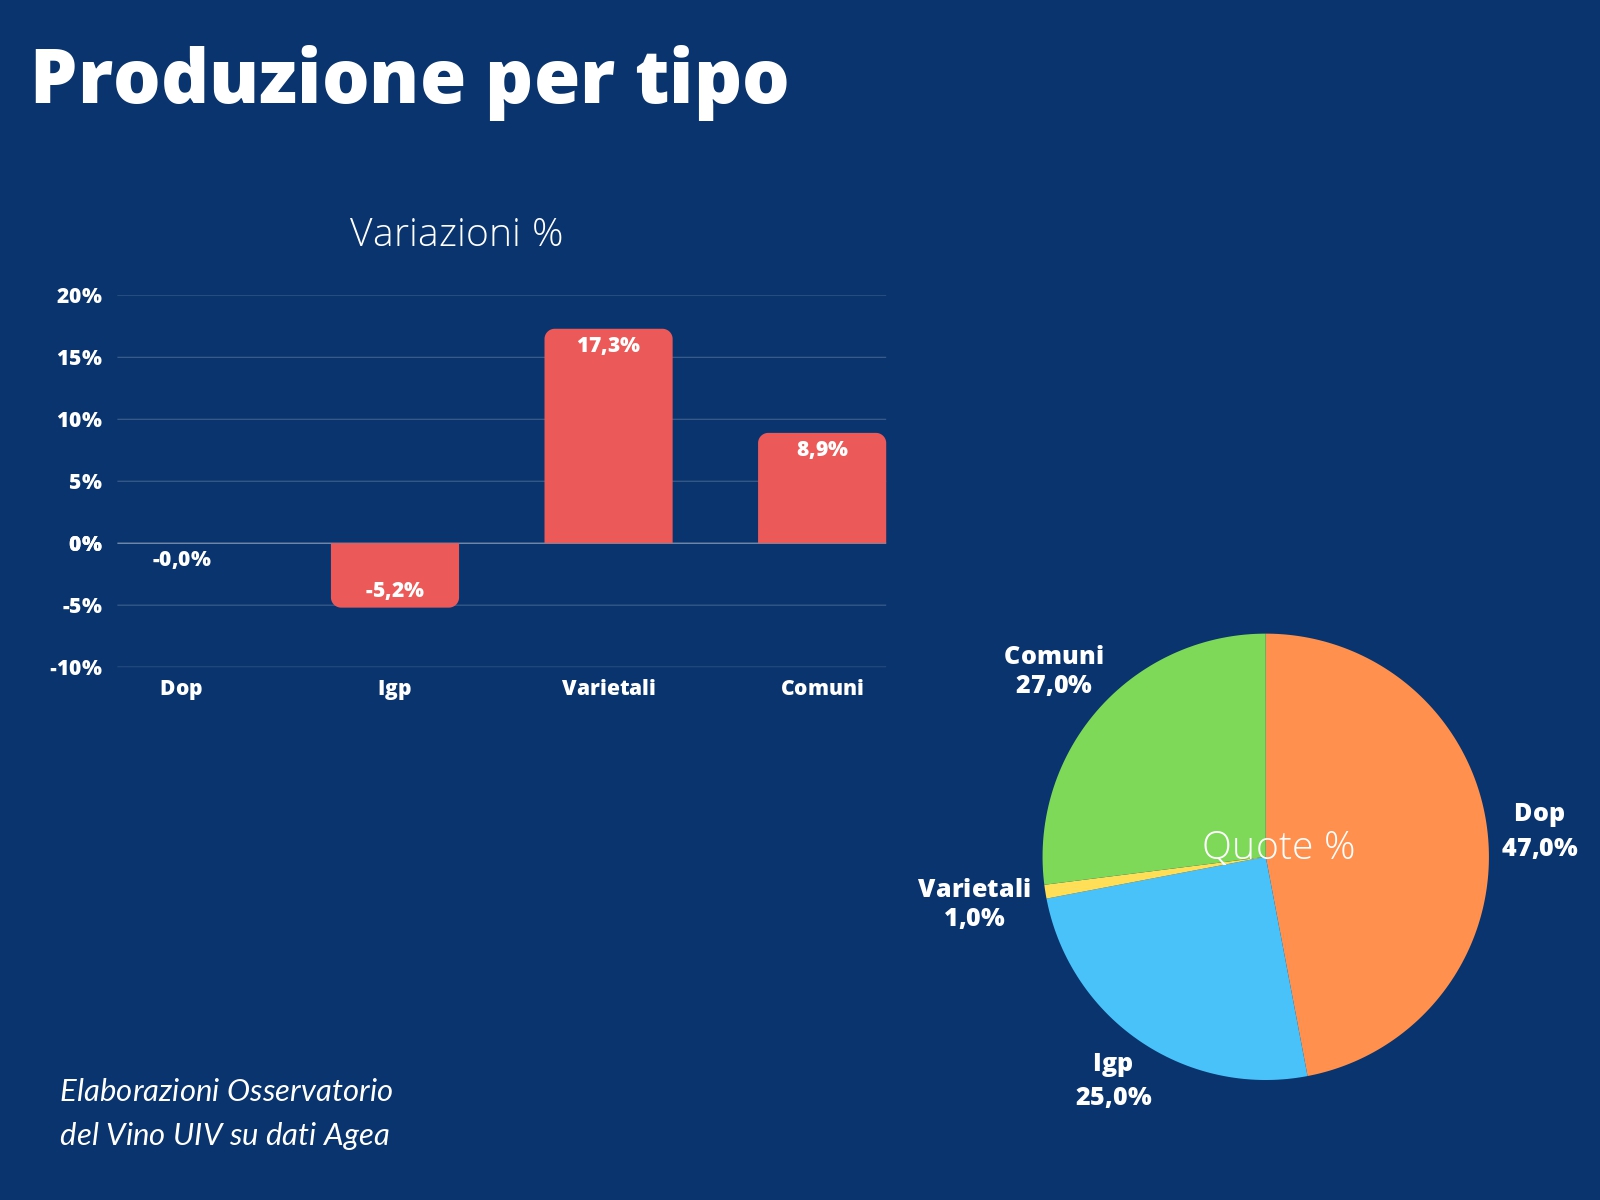
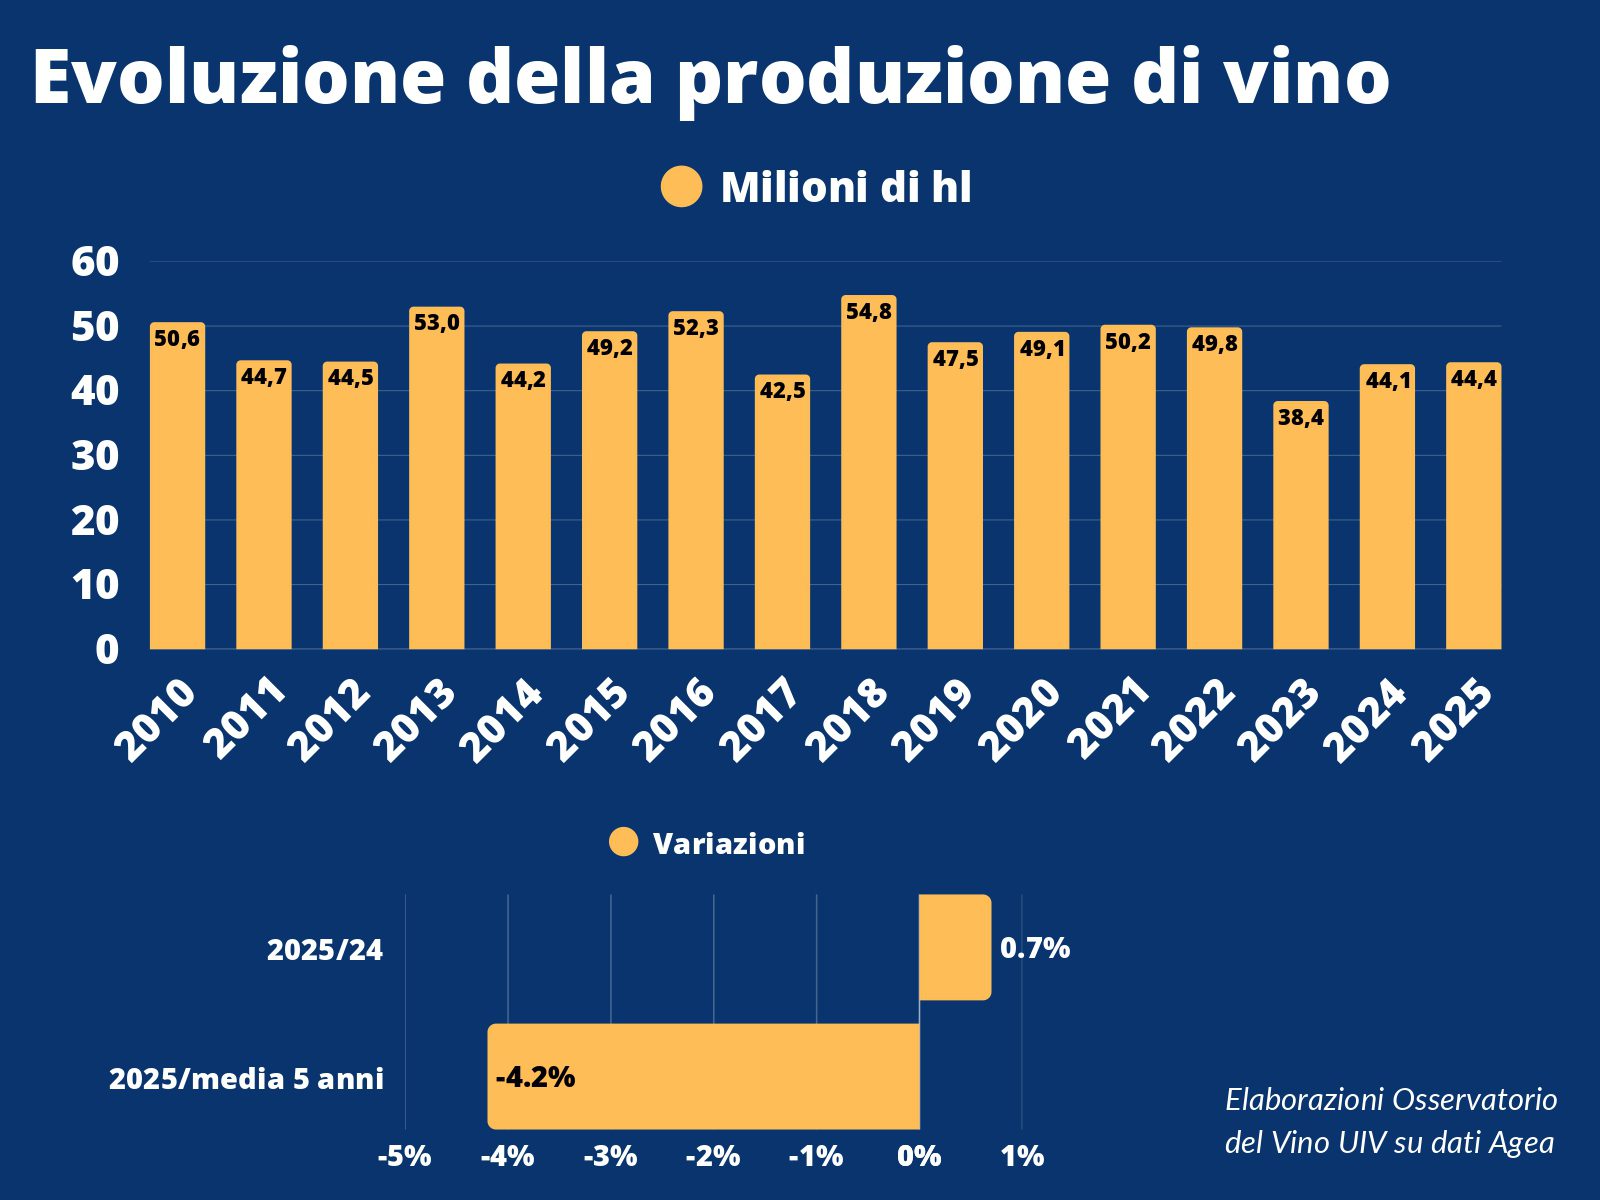
Reporting a stable output of 44.383 million hectoliters, Italy’s 2025 harvest aligns closely with previous year totals (+0.7%), according to official data transmitted to the European Commission. This consistency, as noted by Unione Italiana Vini, results primarily from a calculated reduction in yields across major denominations rather than climatic factors. Yet, such production caps—though aimed at stabilizing the supply chain—have proven insufficient when weighed against current inventory levels.
“Following two harvests just above the 44-million-hectoliter mark, Italian cellars now hold 61 million hectoliters of wine—a 6% increase over the same period last year,” states UIV President Lamberto Frescobaldi. Including musts, the volume reaches nearly 68 million hectoliters (+7.5%). These figures underscore a stark reality: the industry can no longer sustain volumes matching the ten-year average of 47.5 million, nor even the levels of the last biennium previously considered low. Consequently, essential is a centralized revision of the Testo Unico to ensure a flexible production framework capable of contracting or expanding in response to market volatility.
Inventory Surges and Pricing Pressure
Significant surpluses characterize current inventory data, revealing a +11.3% spike for common/varietal wines and a +10.5% surge for white IGTs, while PDO (DOP) stocks show a more contained growth of 3.6% (31.7 million hectoliters).
The situation remains delicate, according to UIV General Secretary Paolo Castelletti, with product outflow slowing by approximately 20%. Such a downturn is evident not only against early 2024—inflated by imminent US tariffs—but also compared to 2023. Despite the lack of an overabundant harvest, bulk wine pricing remains sluggish. White table wines, frequently utilized as sparkling bases, have seen average price drops exceeding 10% in primary producing regions. Even within the appellation segments, upward price trends are rare, with most indicators pointing toward stability or decline.
Strategic Countermeasures for a Shifting Market
Driving these dynamics is a broader market friction, with projections estimating a 7% decline in extra-EU exports by year-end 2025. Addressing such a downturn requires, according to Unione Italiana Vini, a suite of urgent interventions ranging from the reduction of maximum grape yields per hectare—contingent on ending derogations for generic wines—to a rigorous alignment of disciplinary yield caps with actual production averages from the last five years. Furthermore, managing the current surplus necessitates a moratorium on new planting authorizations, a measure intended to halt the annual expansion of the Italian vineyard, which currently increases by nearly 7,000 hectares every twelve months.